
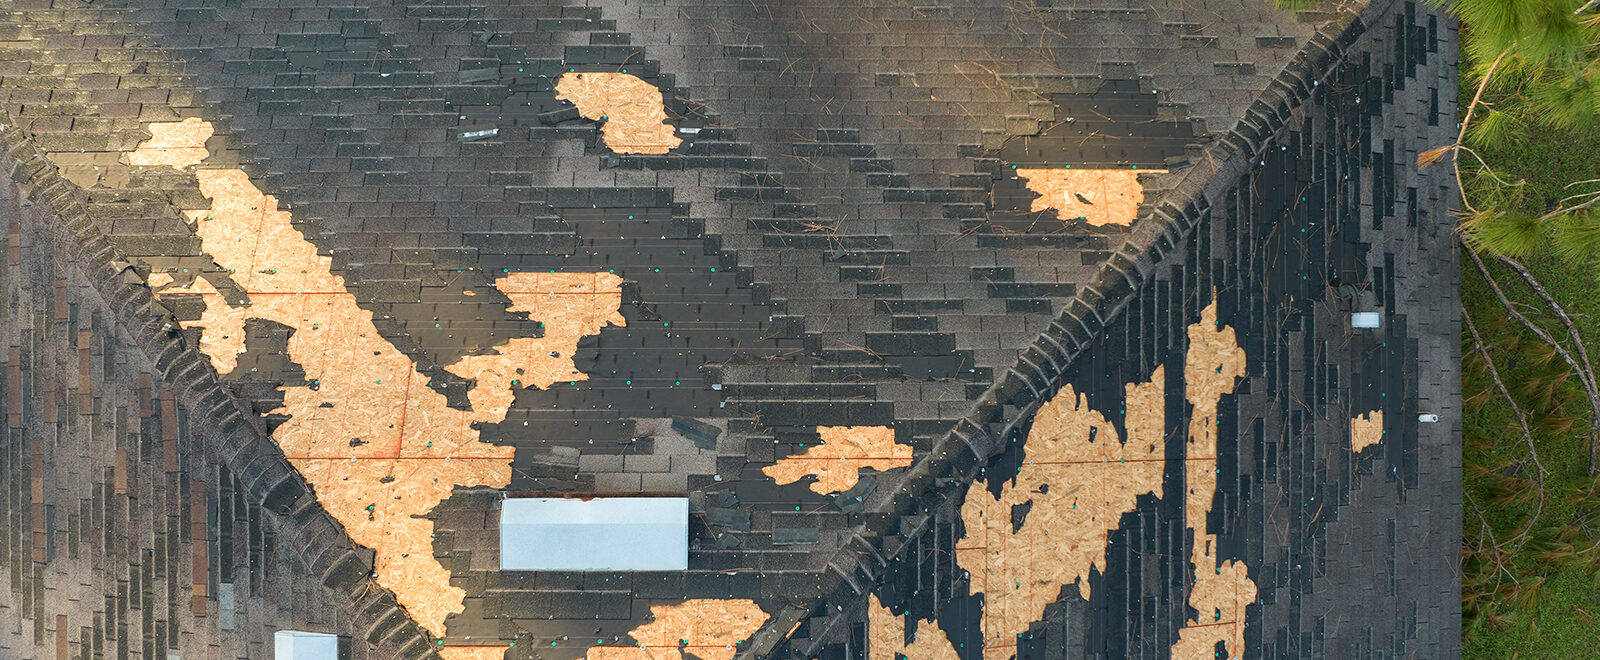
Storms are not occasional events in Texas and Louisiana; they are part of the landscape. In Texas alone, more than 3,600 storm events were recorded in 2024, including hailstorms, high winds, and hurricanes that frequently damage roofs. Across Louisiana, the risk is just as persistent, with an average of 6.8 billion-dollar weather disasters per year in recent years, many tied to severe storms and tropical systems.
Because these storms occur so often, roof damage claims are not uncommon. If you are dealing with a storm damage roof insurance claim, acting quickly can make a meaningful difference. Damage may worsen over time, and delays can complicate how insurers evaluate your claim.
This guide explains what your policy may cover, the steps to take after roof damage, common reasons claims face issues, and when legal support may help protect your rights.
Does Homeowners Insurance Cover Roof Damage from Storms?
In many cases, homeowners insurance does cover roof damage caused by storms, but the extent of coverage depends on your policy terms and the cause of the damage. Most standard policies in Texas and Louisiana include protection against sudden and accidental events, which often apply to storm-related roof damage.
What Types of Storm Damage Are Typically Covered?
Homeowners insurance generally covers roof damage caused by:
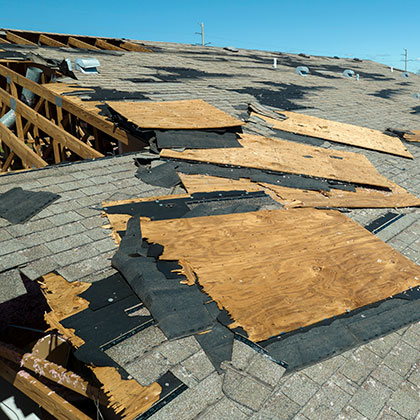
- Windstorms, including high winds that lift or tear shingles
- Hail impacts that crack or puncture roofing materials
- Hurricanes and named storms, subject to specific deductibles
- Falling debris, such as tree limbs, during a storm
Coverage usually applies when the damage is sudden and directly linked to a covered weather event.
What May Not Be Covered?
Not all roof damage qualifies for coverage. Insurance companies often deny or limit claims when:
- The damage results from normal wear and tear or aging
- There was pre-existing damage before the storm
- The roof was not properly maintained over time
- The issue developed gradually rather than from a single event
These exclusions often become key points of dispute in a storm damage roof insurance claim, especially when insurers argue that the damage was not caused solely by the storm.
Actual Cash Value vs. Replacement Cost Value: What It Means for Your Claim
Your payout also depends on how your policy values the roof:
- Actual Cash Value (ACV) factors in depreciation, meaning the insurer pays based on the roof’s current value, not the cost to replace it
- Replacement Cost Value (RCV) covers the cost to repair or replace the roof with similar materials, without deducting depreciation (subject to policy terms)
This distinction directly affects how much the insurer may offer and whether the settlement fully addresses the damage.
Steps to File Storm Damage Roof Insurance Claim
Filing a storm damage roof insurance claim involves more than just reporting the damage. Each step you take after a storm can influence how your claim is reviewed, valued, and ultimately resolved. Acting promptly, staying organized, and understanding what insurers expect can help you avoid common setbacks.
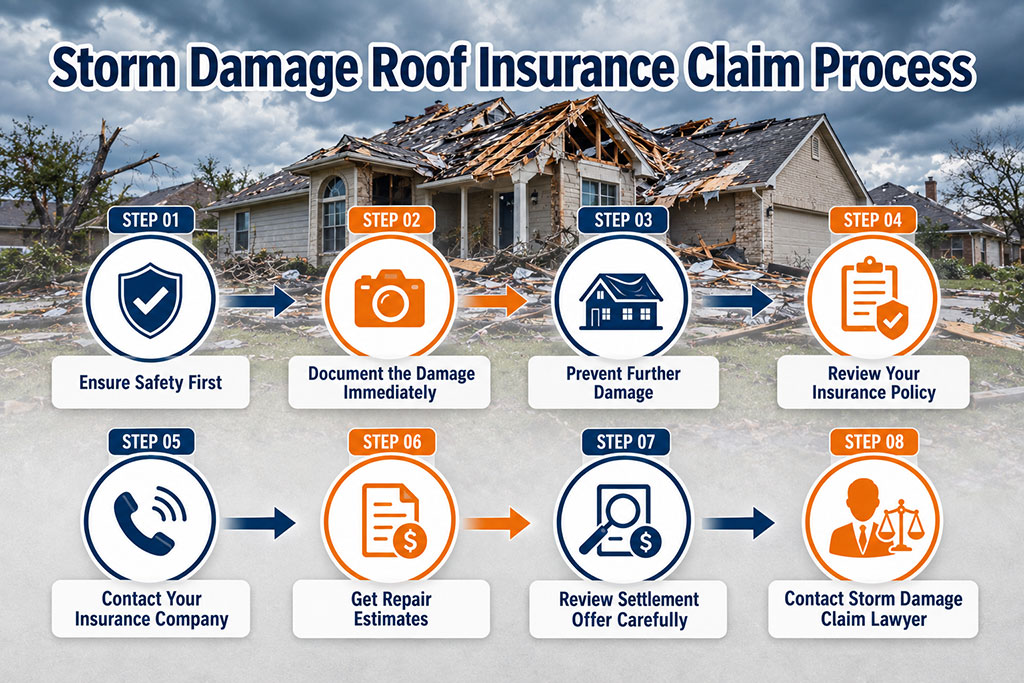
Step 1: Ensure Safety First
Your safety comes before anything else. After a storm:
- Avoid climbing onto the roof, especially if there are signs of structural instability.
- Watch for hazards such as exposed wiring, loose debris, or weakened ceilings.
- If the property feels unsafe, limit access until a professional can assess the damage.
Taking unnecessary risks early on can lead to further harm and complicate your claim.
Step 2: Document the Damage Immediately
Strong documentation is the foundation of a successful storm damage roof insurance claim. As soon as it is safe:
- Take clear photos and videos of roof damage from the ground and surrounding areas.
- Capture interior damage, such as water stains or leaks.
- Include timestamps and note the date of the storm.
- Save weather reports or alerts that confirm the storm event.
Detailed evidence helps establish that the damage is directly tied to the storm.
Step 3: Prevent Further Damage (Mitigation)
Most policies require you to take reasonable steps to prevent additional damage. This may include:
- Placing a tarp over exposed areas of the roof
- Sealing active leaks to limit water intrusion
- Removing debris that could worsen the damage
Keep all receipts and records of any temporary repairs. Insurers often review whether proper mitigation steps were taken when assessing a storm damage roof insurance claim.
Step 4: Review Your Insurance Policy
Before moving forward, take time to understand your coverage. Pay attention to:
- Whether your policy includes wind, hail, or named storm coverage
- Any separate hurricane or windstorm deductibles
- Exclusions that may affect your storm damage roof insurance claim
Knowing your policy helps you set realistic expectations and identify potential issues early.
Step 5: Contact Your Insurance Company
Notify your insurer as soon as possible to initiate the claim. During this step:
- Provide basic details about the storm and observed damage.
- Follow your insurer’s claim reporting requirements.
- Submit initial photos or documentation if requested.
Timely reporting helps prevent disputes about delays.
Step 6: Get Repair Estimates
Obtaining independent repair estimates can provide a clearer picture of the damage. You should:
- Request detailed estimates for repair or replacement
- Compare these with the insurer’s assessment
- Look for gaps where damage may be overlooked or undervalued
This step is important if your storm damage roof insurance claim is undervalued.
Step 7: Review Settlement Offer Carefully
Do not rush to accept the insurer’s first offer. Review it closely to:
- Check whether all visible damage is included in the scope.
- Understand how depreciation has been applied.
- Identify any missing or underpriced items.
If something seems incomplete, you may need to request a reassessment.
Step 8: Contact Storm Damage Claim Lawyer
If your storm damage roof insurance claim is delayed, underpaid, or denied, legal guidance may help protect your interests. A property damage attorney can:
- Review your policy and claim details
- Identify gaps or inconsistencies in the insurer’s evaluation
- Communicate with the insurer on your behalf when disputes arise
Seeking legal support does not mean escalating unnecessarily. It ensures your claim receives a fair and thorough review.
State-Specific Considerations for Storm Damage Roof Insurance Claim
Laws and insurance requirements can vary significantly between states, and those differences can directly affect how a storm damage roof insurance claim is handled. Texas and Louisiana have distinct rules shaped by frequent severe weather events. Understanding these state-specific factors can help you stay compliant with policy requirements, avoid delays, and better prepare for how insurers may evaluate your claim.
Texas Considerations
Texas has specific rules that can directly affect how a storm damage roof insurance claim is handled. Understanding these requirements early can help you avoid procedural issues and strengthen your position.
- The 15/15/5 Timeline: Under the Texas Prompt Payment of Claims Act, insurers must follow a specific timeline:
- The insurer has 15 days to acknowledge your claim, begin its investigation, and request any information needed to evaluate the loss.
- After receiving all requested information, the insurer generally has 15 business days to notify you whether the claim is approved or denied.
- If the claim is approved, payment is typically issued within 5 business days of the approval decision.
- Percentage-Based Deductibles: Many Texas policies use wind and hail deductibles calculated as a percentage of the home’s total insured value rather than a flat dollar amount.
- Prohibition of Deductible Waivers: Per House Bill 2102, it is illegal for contractors to waive or “absorb” a deductible. Homeowners must pay the full deductible and must typically provide proof of payment before the insurer releases final depreciation funds.
- The Appraisal Clause: If you and the insurer agree that there is covered damage but disagree on the cost of the roof, either party can invoke a formal “Appraisal” process to set the binding repair price.
- Weather Verification: Insurers heavily rely on third-party weather data and hail reports to verify that a covered event occurred on the specific date you claimed.
Because Texas insurers closely evaluate both policy compliance and storm evidence, even small gaps in documentation or timing can affect how your claim is reviewed.
Louisiana Considerations
Louisiana presents a different set of challenges and consumer protections, particularly due to frequent hurricanes and severe weather events. These factors shape how a storm damage roof insurance claim may be evaluated.
- Annual Deductible Law: A vital protection in Louisiana is that “Named-Storm” deductibles apply on an annual basis. If you pay your full hurricane deductible for one storm, you generally do not have to pay it again for a second storm in the same calendar year.
- Claim Payment Deadlines and the “Cure Period”: Under La. R.S. 22:1892, for non-catastrophic claims, insurers must generally pay within 30 days after receiving “satisfactory proof of loss.” For claims involving declared catastrophes (specifically immovable property like your home), regulations require a 60-day written notice before filing a bad-faith lawsuit.
- Contractor Licensing Threshold: As of 2026, any roofing project exceeding $7,500 requires a state-licensed contractor. Using an unlicensed roofer for large storm repairs can lead to claim complications or denials.
- Supplemental Claims: Louisiana policyholders have the right to file supplemental claims if additional “hidden” roof damage, such as decking rot or structural issues, is discovered during the teardown process.
- Regulatory Guidance: Agencies like the Louisiana Department of Insurance (LDI) provide oversight, and programs such as the Fortify Homes Program may offer grants to help homeowners upgrade roofs to stronger “FORTIFIED” standards during the recovery process.
Given the complexity of storm-related claims in Louisiana, careful documentation and ongoing review play a key role in protecting your rights.
What If Your Roofing Insurance Claim for Storm Damage Gets Denied?
A denied or underpaid roofing insurance claim for storm damage can feel frustrating, especially when the damage is clearly visible. However, a denial does not always mean the process is over. Understanding why claims are denied and how to respond can help you take the next steps with confidence.
Common Denial Reasons
Insurance companies may deny or limit a roofing insurance claim for storm damage for several reasons, including:
- The insurer determines the damage is due to wear and tear rather than a covered storm event.
- The roof shows signs of pre-existing damage before the reported storm.
- The insurer believes there was improper maintenance or repair work done over time.
- There is insufficient documentation linking the damage to the storm.
- The claim was reported too late, raising questions about when the damage occurred.
- The insurer claims the damage resulted from an excluded peril, such as flooding, instead of wind or hail.
- Weather data does not clearly support a direct link between the storm and the damage.
- The policy includes coverage limitations based on roof age or material type.
- The insurer considers the damage cosmetic rather than functional, especially in hail claims.
- There are inconsistencies or gaps in the claim information submitted.
- The scope of damage is disputed, particularly in repair versus replacement or partial versus full roof replacement situations.
These issues often become points of negotiation, especially when the insurer’s assessment differs from independent findings.
Appeal Process
If your roofing insurance claim for storm damage is denied, you can take steps to challenge the decision:
- Request a written explanation outlining the specific reason for the denial.
- Submit additional documentation, including photos, reports, or weather records.
- Arrange for an independent inspection to reassess the extent of roof damage.
- File a formal appeal with the insurance company, following their procedures.
- Contact a property damage attorney to review your claim and identify potential gaps or disputes.
Taking a methodical approach can help ensure your claim receives a thorough and fair evaluation.
Tips to Maximize Your Storm Damage Roof Insurance Claim
Maximizing a storm damage roof insurance claim starts with being proactive, organized, and informed. Small mistakes early in the process can affect how your claim is evaluated later.
- File your claim as soon as possible after the storm to avoid disputes around delays.
- Do not rely only on the insurer’s inspection; consider independent evaluations for a complete damage assessment.
- Keep all receipts, invoices, and records related to temporary repairs and mitigation efforts.
- Document everything thoroughly, including photos, videos, and notes tied to the storm date.
- Avoid accepting quick settlement offers without reviewing the full scope of damage.
- Review your policy carefully so you understand coverage limits, deductibles, and exclusions.
- Do not sign an Assignment of Benefits (AOB) without fully understanding its implications.
- Maintain clear communication records with your insurance company, including emails and claim updates.
- Track all deadlines and requests from the insurer to stay compliant with policy requirements.
- Be cautious of incomplete or vague repair estimates that may undervalue the damage.
Taking these steps can help you stay in control of your claim and reduce the risk of underpayment or unnecessary delays.
Conclusion
Handling a storm damage roof insurance claim requires timely action, clear documentation, and a solid understanding of your policy. From the initial inspection to reviewing settlement offers, each step plays a role in how your claim is evaluated. While many claims move forward without issue, others may involve delays, disputes, or underpayment. In those situations, having the right guidance can make the process easier to navigate.
If your claim becomes complicated or you are unsure about the next steps, speaking with the team at Pandit Law for a free claim evaluation can help you better understand your options and next steps.
Frequently Asked Questions
Avoid making assumptions about the cause of damage, downplaying issues, or speculating about repairs. Stick to factual observations and documented evidence. Inconsistent or unclear statements can affect how your claim is evaluated.
Homeowners insurance may cover a leaking roof if the leak results from sudden storm damage. It typically does not cover leaks caused by wear and tear, aging, or lack of maintenance over time.
Coverage depends on the extent of the damage and policy terms. If damage is widespread, replacement may be considered. If damage is limited, insurers may approve repairs instead of full replacement.
Homeowners insurance may cover a new roof when storm damage significantly impacts its structure or function. Coverage depends on policy terms, cause of damage, and whether the loss is considered sudden and accidental.